Why gross margin and markup needs a defined workflow
Teams sometimes use margin and markup interchangeably even though they calculate return from different bases and produce different selling prices.
The objective is not to remove judgment from gross margin and markup. It is to organize the evidence, calculations and unresolved questions so the right person can make a faster and better informed decision.
A practical operating method
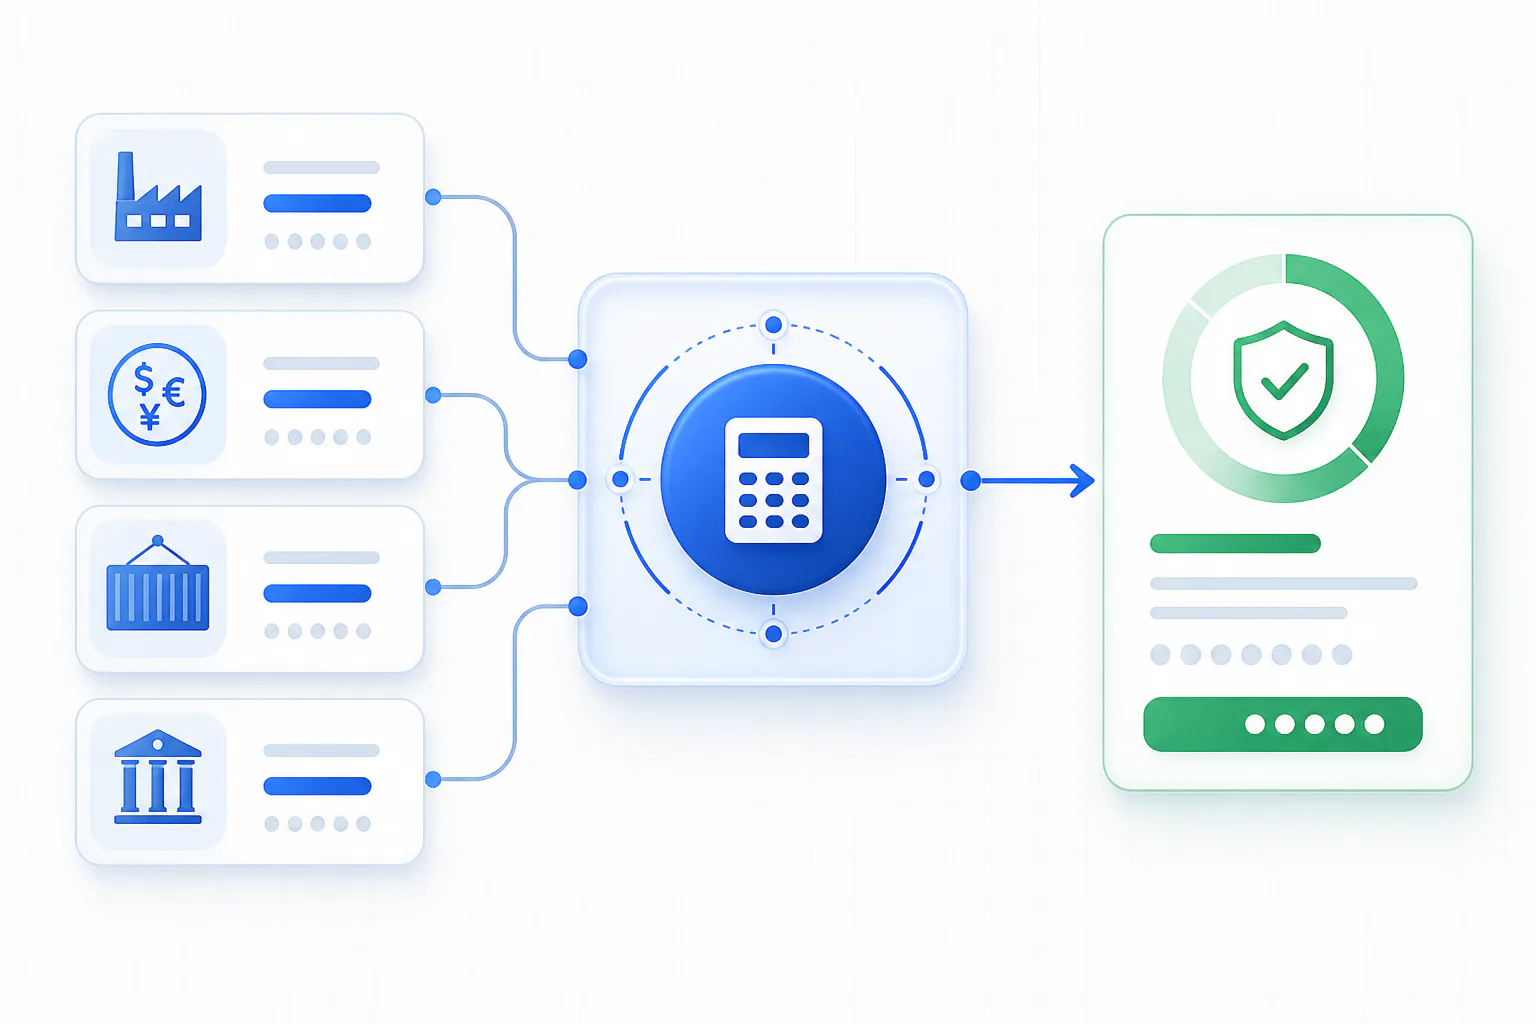
Label the required measure explicitly, calculate it from a verified landed cost and show the cost, sell price and resulting percentage together.
Keep the original customer and supplier language beside every normalized field. When information conflicts or support is missing, show the exception instead of inventing an answer.
Controls to include
The workflow should make important controls visible at the moment they affect the quotation. These controls help reviewers distinguish routine preparation from decisions that create technical or commercial exposure.
- Measure clearly labelled
- Verified cost basis
- Approved pricing rule
- Reviewer visible calculation
What good implementation looks like
Commercial reviewers can confirm that a quotation meets the intended return before the price reaches the customer.
Test the approach with cases the team already understands. Review the evidence, corrections and decision quality before connecting live systems or expanding external actions.
Questions for the operating review
A useful review of gross margin and markup should focus on the decisions the workflow supports, the evidence available to the reviewer and the consequence of an unresolved exception.
- How is measure clearly labelled verified, owned and recorded?
- How is verified cost basis verified, owned and recorded?
- How is approved pricing rule verified, owned and recorded?
- How is reviewer visible calculation verified, owned and recorded?
How to measure improvement
Measure whether the new method produces commercial reviewers can confirm that a quotation meets the intended return before the price reaches the customer.
Pair preparation speed with correction load, missing evidence, exception quality and reviewer confidence. The process is improving only when the team reaches a sound decision with less reconstruction and no hidden increase in technical or commercial risk.